These days, more and more companies are calling themselves AI companies. But what does that label actually tell us?
University of Washington Foster School of Business professors Suresh Kotha and Ming zhu Wang set out to answer that question by analyzing more than 77,000 companies categorized as AI or machine learning companies in PitchBook, a database that tracks private companies, venture capital, and other investment activity. What they found was a far more complex AI economy than the broad “AI company” label suggests.
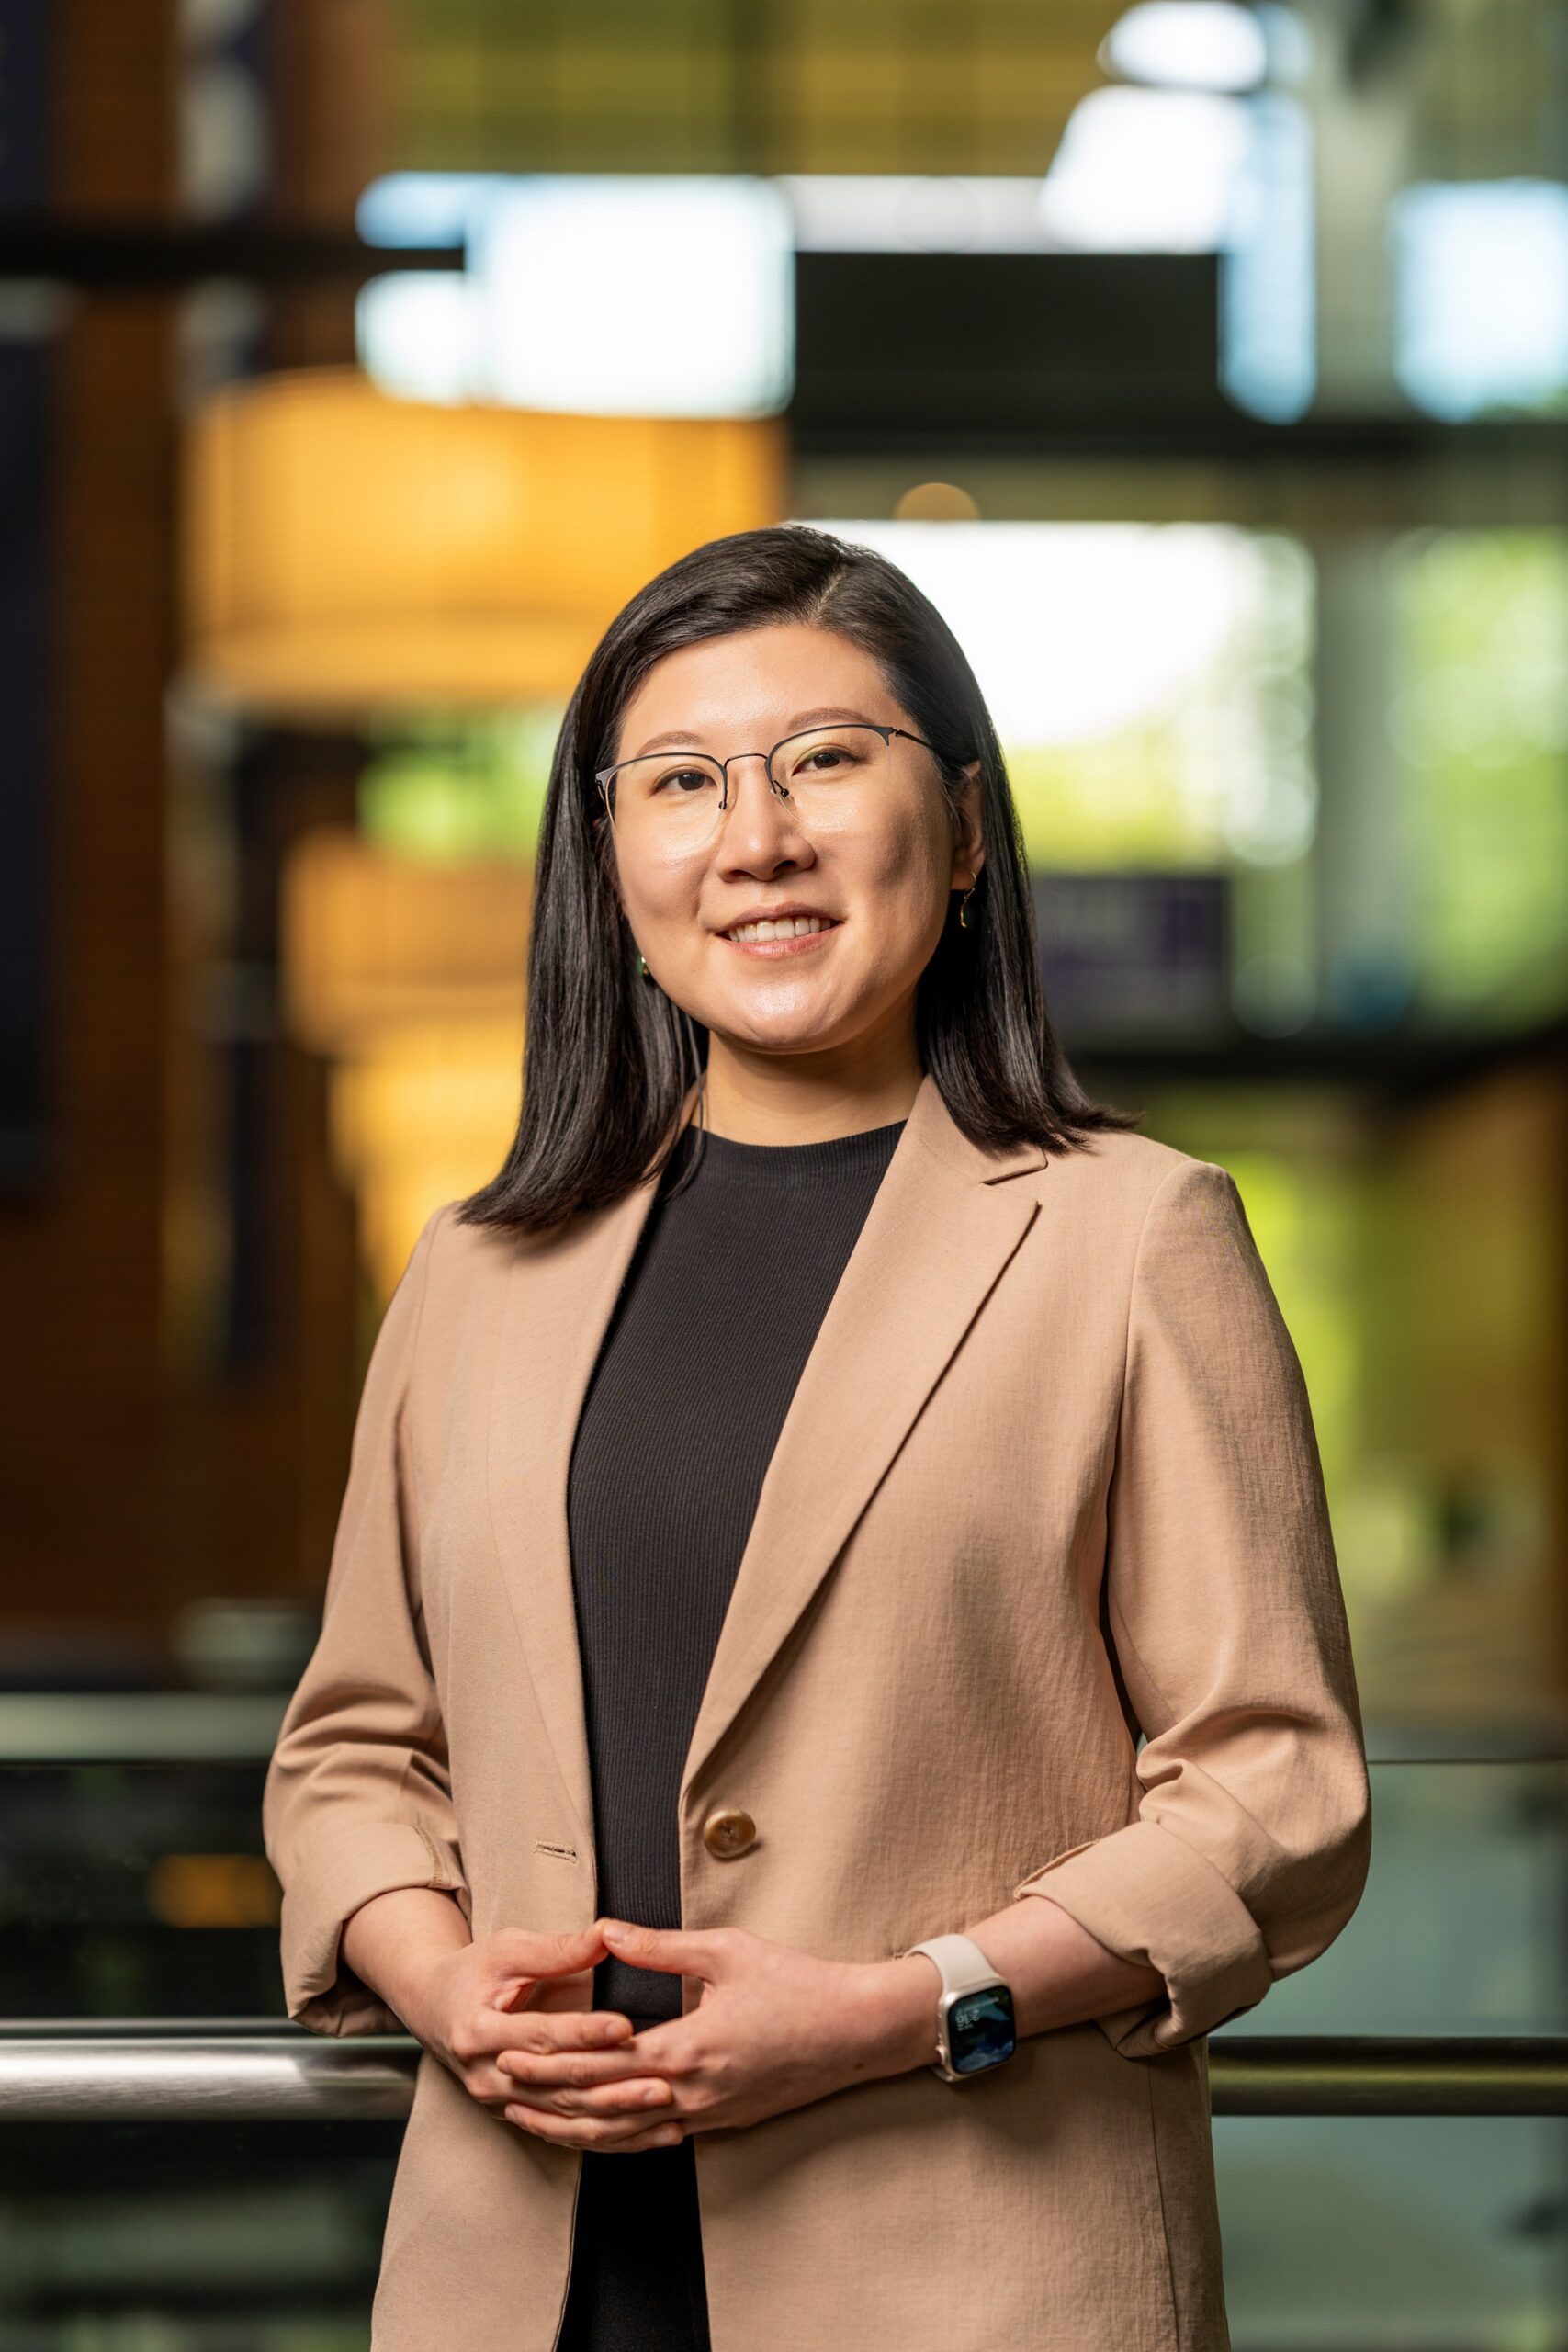
Ming zhu Wang, above, and Suresh Kotha reveal a surprising divide in the AI economy: The companies attracting the most investment aren’t necessarily creating the most jobs.
“There is no such thing as AI companies” as a single category, said Kotha, the Battelle/Olsen Excellence Chair in Entrepreneurship. Instead, the companies fall into what the researchers describe as five distinct layers based on the role AI plays in their products and services. Some build the computing infrastructure or models that make AI possible. Some build products around the technology. Others add AI features to existing products or provide human-related services that support the industry.
Those distinctions matter, Kotha and Wang argue, because broad claims about “AI companies” can obscure what is actually happening with products, investment, and jobs.
When the label changes faster than the product
One of the report’s clearest findings is that, after the introduction of ChatGPT in November 2022, companies changed how they described themselves far more often than they fundamentally changed what they sold. In the second half of 2025, for every company that changed its core product to rely on AI, 19 began presenting themselves as AI companies.
Wang, assistant professor of strategy and entrepreneurship, said one reason for the gap is simple: Changing how a company describes itself is relatively cheap.
“Maybe previously you were a data analytics company, now let’s just call your product AI-powered,” she said. “And then just change one line on your homepage.”
Actually changing the product is considerably more difficult, she added.
That doesn’t mean companies are trying to mislead anyone. Kotha cautioned against assuming motives the researchers cannot observe. Venture-backed companies are built to pursue rapid growth, he noted, and AI as a category has attracted enormous amounts of money and attention. Repositioning around AI can therefore be a rational response to the market.
Follow the money — and the jobs
Companies that add AI capabilities to existing products make up about 41% of the companies in the analysis. Companies selling products in categories created by modern AI account for only 13%.
Yet that smaller group received more than half of venture funding from early 2023 through early 2026. That money is also highly concentrated: OpenAI, Anthropic, and xAI alone received 37% of venture capital flowing to the AI companies studied.
That means headlines about soaring investment in AI can give a misleading picture of how broadly that money is being distributed. As Kotha put it, statistics about the AI economy need to be accompanied by a basic question: Which companies are we talking about?
Another insight from the report is that the companies attracting the most investment are not the ones employing the most people.
The companies in the report accounted for about 1.8 million jobs in early 2026. Nearly half were at companies that add AI capabilities to existing products, compared with about 8% at companies selling products in categories created by modern AI.
Wang thinks that distinction may be especially important for policymakers and the broader public.
“We hear a lot of talk about how these AI technologies, yes, they might displace some jobs, but there’s also the potential to create new jobs,” she said. “Where are the jobs associated with AI actually showing up, and what do they look like? This is something we looked at.”
For now, the report suggests that much of the employment associated with AI is not at the headline-grabbing startups building entirely new AI products. It is at companies incorporating the technology into products they already offer.

Suresh Kotha, above, and Ming zhu Wang found that adopting the AI label is far more common than fundamentally changing a company’s product.
We’ve seen this pattern before
Kotha sees parallels between today’s AI boom and earlier waves of technological change, including the dot-com era: investment pours in, new companies proliferate, and, eventually, the field thins.
“A lot of money coming in, lots of players getting funded, and then a few players get left over,” he said. “This plays out in every technological change.”
Exactly how the AI economy will shake out remains uncertain. The researchers emphasize that their report captures only a snapshot of a fast-moving market, and one limited to the venture-oriented companies in their PitchBook analysis rather than the full universe of businesses using AI.
And the availability of this kind of detailed data gives researchers an unusual opportunity to watch the market evolve. Wang is excited by the prospect of tracking where companies are forming, where jobs and investment are flowing, and where founders are coming from. This kind of information simply wasn’t available during the dot-com boom, much less for an earlier transformation like electrification.
What comes next remains to be seen. But as the AI economy evolves, understanding it will require looking beyond the broad “AI company” label to the very different businesses behind it.
Read the AI Economy in Five Layers Report |
Read the AI Economy in Five Layers Regional Report: Seattle and Five Peer AI Hubs |
Suresh Kotha is a Professor of Management, the Olesen/Battelle Excellence Chair in Entrepreneurship, and the Research Director of the Arthur W. Buerk Center for Entrepreneurship at the University of Washington Foster School of Business.
Ming zhu Wang is an Assistant Professor of Strategy and Entrepreneurship at the University of Washington Foster School of Business.